Should I Change My 401(k) Investments? What to Consider First
Takeaways
- Most 401(k) plans let you change your investments online at any time, though some funds may limit frequent trading.
- Changing where future contributions go and changing how your current balance is invested are two separate steps.
- Life changes, a shift in your risk tolerance and portfolio drift may be good reasons to review your investments.
- Reacting to headlines or chasing last year’s top-performing fund may work against your long-term goals.
- A regular review schedule may help you make changes on purpose, not out of fear.
Should I Change My 401(k) Investments Right Now?
Maybe the market just dropped. Maybe it’s been climbing for months and you’re wondering if you’re missing out. Maybe you logged in for the first time in a while and didn’t recognize what you saw.
Whatever brought you here, it’s a fair question to ask.
An answer: It depends on why you want to make a change.
Some reasons to adjust your 401(k) are sound. Others may do more harm than good. This guide can help you tell the difference.
Two Different Changes: Future Contributions vs. Your Current Balance
Before you change anything, it helps to know that most 401(k) plans treat these as two separate decisions.
1. Changing your future contributions. This tells your plan how to invest the money from your next paycheck forward. It does not touch the money already in your account.
2. Changing your existing balance. This is sometimes called a reallocation, exchange or transfer. It sells some of your current investments and buys others.
Many savers update one and forget the other. For example, you might change your future contributions to a more conservative mix, while your existing balance, often the much larger amount, stays exactly where it was.
If you want your whole account to reflect a new strategy, you may need to make both changes.
How Often Can You Change Your 401(k) Investments?
In most plans, you can change your investments as often as you like, usually online or through your plan’s app.
There are a few exceptions to know about:
- Frequent-trading rules. Some funds restrict how soon you can buy back into a fund after selling it, or charge a short-term redemption fee. Your plan documents will spell these out.
- Blackout periods. If your employer switches 401(k) providers, you may temporarily be unable to make changes during the transition.
- Timing. Changes are typically processed at the end of the trading day, not instantly.
One helpful detail: Buying and selling inside your 401(k) doesn’t create a tax bill. Taxes generally apply only when you withdraw money from the account.
So the question usually isn’t can you change your investments. It’s whether you should.
Good Reasons to Consider Changing Your 401(k) Investments
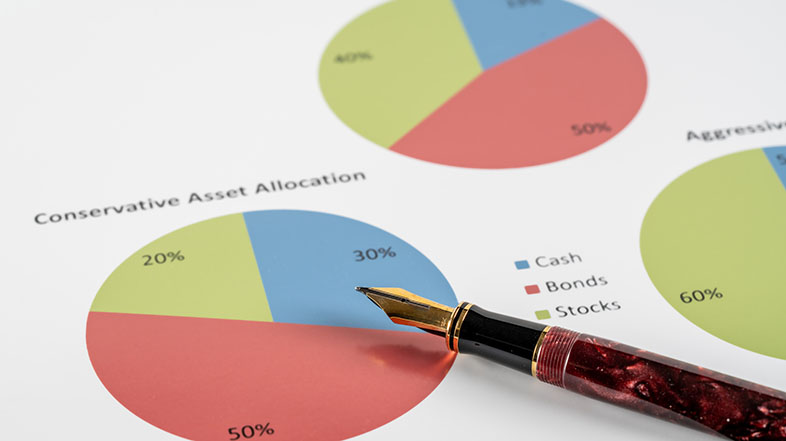
These are some situations where a review, and possibly a change, may make sense:
- You’re getting closer to retirement. As your timeline shortens, protecting what you’ve built may become as important as growing it.
- Your risk tolerance has changed. If market swings are keeping you up at night, or you realize you’ve been more conservative than you need to be, your mix may no longer fit you.
- Your portfolio has drifted. Even if you never make a change, market movements shift your mix over time. A 70/30 stock-to-bond mix might drift to 76/24 after a strong stock market. Here’s why rebalancing matters.
- A major life event happened. Marriage, divorce, a new child, a job change or a health issue can change how much risk you’re able to take.
- Your plan changed its fund lineup. When funds are added or replaced, your money may be moved into a default option you didn’t choose.
- You’re paying more than you need to. If your plan offers lower-cost funds with similar exposure, it may be worth a look.
- You’re too concentrated. Holding a large share of your account in a single fund, sector or your employer’s stock may increase your risk.
When It May Make Sense to Hold Steady
Some of the most common reasons people change their 401(k) investments are also the ones that can work against them.
- Reacting to a market drop. Selling after a decline turns a paper loss into a real one. Then you have to decide when to get back in, and get that timing right, too.
- Chasing last year’s winner. A fund’s strong recent performance doesn’t mean it will continue. Past performance doesn’t guarantee future results.
- Acting on headlines. News moves fast. Your retirement timeline usually doesn’t.
- Trying to time the market. Moving everything to cash and waiting for the “right moment” is a difficult strategy to get right consistently.
None of this means you should never make a change. It means the reason behind the change can matter.
What Should You Do With Your 401(k) During a Market Downturn?
Market downturns are when the urge to make a change is often strongest.
A few things to consider before you act:
- Revisit your time horizon. If retirement is years away, short-term declines may matter less than your long-term plan.
- Keep contributing if you can. Regular contributions buy more shares when prices are lower. This approach, called dollar-cost averaging, doesn’t guarantee a profit or protect against loss, but it keeps you investing on a consistent schedule.
- Review, don’t react. A downturn can be a good time to check whether your allocation still matches your risk tolerance. Rebalancing back to your target is different from abandoning your strategy.
More on managing your 401(k) during market volatility.
A Note on Target-Date Funds
Many 401(k) savers are invested in a target-date fund, either by choice or as their plan’s default.
A target-date fund is designed to be a complete portfolio on its own. It holds a mix of stocks and bonds that typically becomes more conservative as the target year approaches.
If you add other funds on top of a target-date fund, you may unintentionally double up on certain investments or change the fund’s intended risk level. Before mixing, it may help to understand what the target-date fund already holds.
Target-date funds aren’t right for everyone. Two people retiring the same year may have very different savings, income needs and comfort with risk.
Questions to Ask Before You Change Your 401(k) Investments
Run through this checklist before you click “submit”:
- Why do I want to make this change, and would I feel the same way if the market hadn’t moved this week?
- Does my new mix match how many years I have until retirement?
- Am I changing future contributions, my current balance, or both?
- Do any of my funds have trading restrictions or fees?
- What are the expense ratios of the funds I’m moving into?
- Am I doubling up on anything I already own?
- When will I review this again?
That last question may be the most important one. A set review schedule, such as quarterly, may help you make changes on purpose instead of in the moment.
Should You Get Help Managing Your 401(k) Investments?
You can manage your 401(k) investments on your own.
But if you’re unsure whether your current mix fits your goals, or you’d rather not make these decisions every time the market moves, professional guidance may help.
401(k) Maneuver provides independent, professional account management for the 401(k) you already have through work. Your account stays with your current plan provider, and we work within the investment options your plan offers.
Here’s what you can expect as a 401(k) Maneuver client:
- Professional quarterly 401(k) account rebalancing, personalized to your tolerance for risk and based on current economic and market conditions.
- An email notification every time we review your account.
- Membership in our online community, with content to help you prepare for retirement.
- Access to a private Facebook group where you can ask our advisors questions.