401(k) Asset Allocation by Age: Common Approaches and Their Limits
401(k) asset allocation by age starts with your timeline
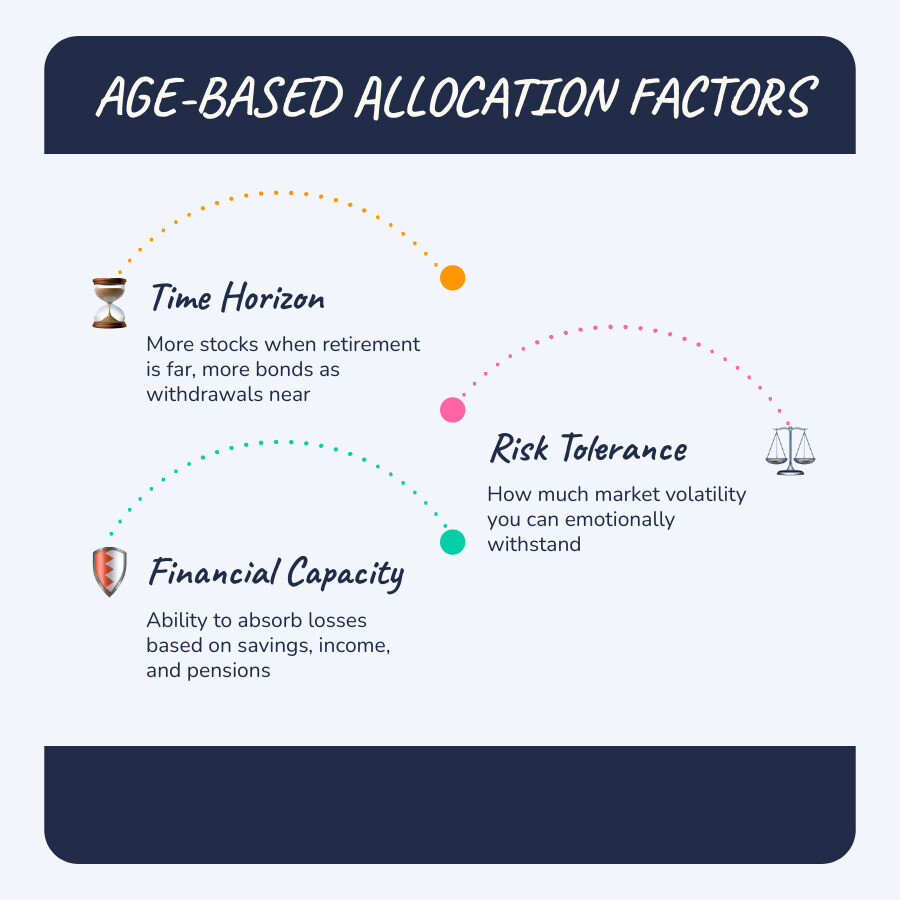
To set your 401(k) asset allocation by age, start with when you expect to use the money. A common approach is to hold more stocks when retirement is far away, then gradually add bonds as withdrawals get closer. Keep some stocks in retirement for long-term growth, and choose cash based on your near-term spending needs.
Age-based formulas are starting points, not instructions. Your mix should include how much market risk you can tolerate and how much loss your finances can absorb. Pension income, savings outside your 401(k), and your retirement date may change the answer. The 401(k) Maneuver team looks at those factors alongside age.
401(k) asset allocation by age: Rules of thumb vs. individual reality
Many investors encounter basic rules of thumb when deciding how to divide their retirement contributions among stocks, bonds, and cash. A classic heuristic suggests subtracting your age from 100 to determine your equity percentage, placing the remainder in fixed income. Under this formula, a 30-year-old would hold 70% in stocks and 30% in bonds, while a 60-year-old would hold 40% in stocks and 60% in bonds.
While simple heuristics provide a general framework for thinking about risk reduction over time, they are not official investment rules. In their investor education resources on asset allocation and diversification, the U.S. Securities and Exchange Commission (SEC) notes that choosing an appropriate asset mix requires balancing risk tolerance, financial goals, and investment timeframes rather than relying on a rigid formula.
The evolution of age-based formulas
As average lifespans have increased and interest rate environments have shifted over recent decades, traditional formulas have evolved. Many practitioners now reference “110 minus your age” or “120 minus your age” as updated benchmarks. Under a 120-minus-age baseline, a 40-year-old might hold 80% equities and 20% fixed income, preserving a higher growth component to help counter long-term purchasing power risk.
Relying entirely on a fixed mathematical subtraction, however, overlooks how individual cash needs vary. An investor who plans to work until age 70 has different growth requirements than someone targeting early retirement at 55.
Generic glide paths and automated allocation
Target-date funds (TDFs) apply this age-based principle automatically through a pre-set “glide path,” which gradually decreases equity exposure as a specified target year approaches. According to the Employee Benefit Research Institute (EBRI) and Investment Company Institute (ICI) 401(k) database, target-date funds accounted for roughly 31% of total plan assets and were utilized by 59% of participants at year-end 2020.
While automated glide paths can provide convenient diversification, they apply a single asset mix to everyone sharing an expected retirement year. A standardized fund cannot account for your personal debt levels, health considerations, or outside taxable savings accounts.
Hypothetical allocation models across career stages
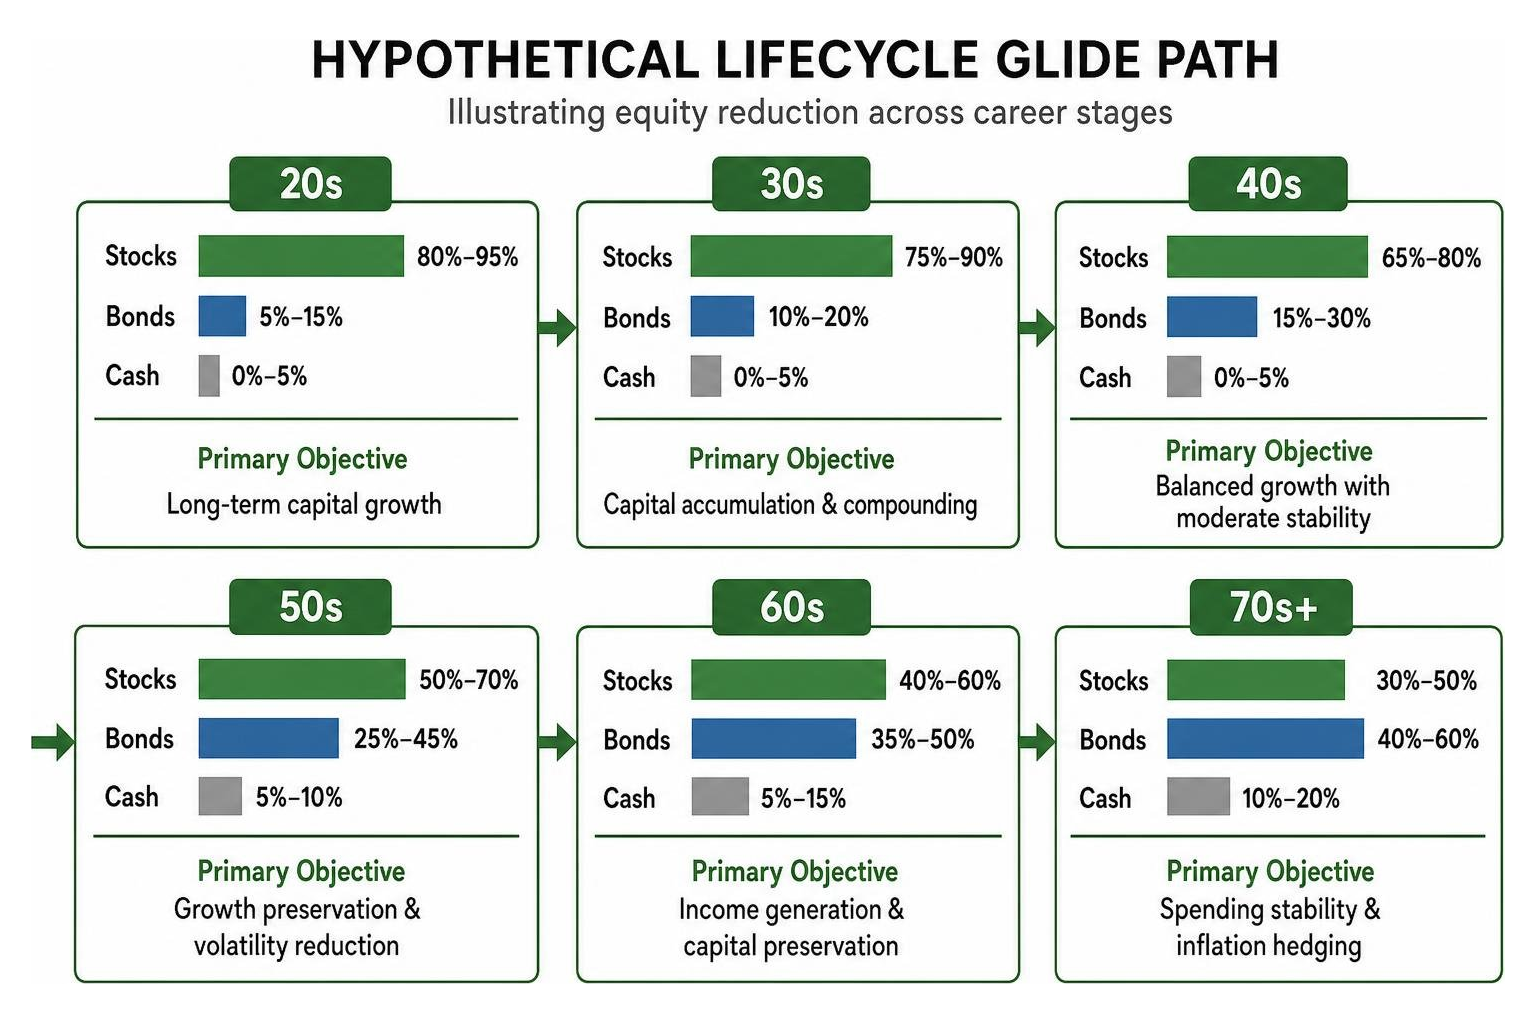
Asset allocation generally transitions through distinct phases as your investment horizon shortens: wealth accumulation in early career, balanced growth in mid-career, and capital preservation alongside income generation near retirement.
The table below illustrates hypothetical portfolio models across different life stages. These examples are provided strictly for educational purposes and do not represent individualized investment advice or guaranteed outcomes.
| Life Stage / Age | Hypothetical Stocks % | Hypothetical Bonds % | Hypothetical Cash % | Primary Portfolio Objective |
|---|---|---|---|---|
| 20s | 80%–95% | 5%–15% | 0%–5% | Long-term capital growth |
| 30s | 75%–90% | 10%–20% | 0%–5% | Capital accumulation & compounding |
| 40s | 65%–80% | 15%–30% | 0%–5% | Balanced growth with moderate stability |
| 50s | 50%–70% | 25%–45% | 5%–10% | Growth preservation & volatility reduction |
| 60s | 40%–60% | 35%–50% | 5%–15% | Income generation & capital preservation |
| 70s+ | 30%–50% | 40%–60% | 10%–20% | Spending stability & inflation hedging |
Baseline 401(k) asset allocation by age across career decades
In your early career, time is your greatest asset. Focusing on saving for retirement in your 20s with a heavy equity tilt allows your portfolio several decades to navigate market cycles and benefit from compounding returns.
By mid-career, responsibilities often increase alongside peak earning years. If your retirement savings lagged earlier in life, catching up on savings after age 40 may require higher contribution rates alongside a balanced allocation that prevents unneeded volatility while maintaining healthy growth exposure.
Why 401(k) asset allocation by age must account for market risk near retirement
As you approach retirement age, the order and timing of investment returns—known as sequence of returns risk—becomes critical. Experiencing a sharp market decline in the years immediately preceding or following retirement can significantly affect how long a portfolio lasts when you are simultaneously making regular withdrawals.
To manage this risk, investors in their 50s and 60s often shift a larger portion of assets into fixed-income securities and stable cash buffers, which can provide spending stability without forcing the sale of equities during a market downturn.
Key factors beyond age that influence your portfolio mix

Chronological age is only one variable in portfolio design. Two investors of the exact same age may require vastly different portfolio allocations based on their overall financial picture, household balance sheet, and personal preferences.
Risk tolerance vs. risk capacity
An effective investment strategy balances two distinct concepts:
- Risk Tolerance: Your emotional or psychological comfort with market fluctuations and temporary declines in account value.
- Risk Capacity: Your actual financial ability to absorb portfolio losses without derailing your basic living needs or retirement timeline.
A young professional may have high risk capacity due to a 35-year time horizon, but low emotional risk tolerance if market downturns cause them to panic and sell. Conversely, an investor nearing retirement might have an aggressive appetite for risk but limited financial capacity to absorb a severe drawdown before scheduled distributions begin.
Integrating outside income sources and special circumstances
Outside assets and guaranteed income streams can significantly alter your required 401(k) asset allocation:
- Defined Benefit Pensions & Military Retirement: Predictable monthly pension checks function similarly to fixed-income distributions, which may allow an individual to hold a higher equity allocation within their 401(k).
- Social Security Timing: Delaying Social Security benefits up to age 70 increases guaranteed monthly income later, which can influence how much liquidity is required from personal savings in early retirement.
- Real Estate & Taxable Brokerage Accounts: External rental income or liquid emergency reserves reduce reliance on workplace retirement balances for unexpected short-term cash needs.
- Early Retirement Goals: Individuals planning to leave the workforce prior to standard retirement ages need an allocation designed to support a longer distribution timeframe, which may require sustained equity exposure.
Managing and rebalancing your allocation over time

Over time, different asset classes perform at varying rates, causing your actual holdings to drift away from your original target percentages. A period of strong equity market performance, for example, can unintentionally increase the stock percentage of your portfolio, exposing you to more risk than intended.
Reviewing your account and understanding the process of rebalancing a 401(k) helps restore your chosen targets in a disciplined manner.
Common triggers for portfolio reviews include:
- Reaching regular calendar intervals (such as quarterly or annual reviews).
- Asset class weighting drifting by more than 5% from target allocations.
- Major life milestones, such as marriage, a career transition, or approaching a planned retirement date.
- Changes in household health status or unexpected long-term financial obligations.
Periodic vs. threshold-based rebalancing
Investors generally manage asset drift using either scheduled periodic adjustments (such as quarterly reviews) or threshold-based rebalancing, where trades occur only when an asset class deviates by a specified percentage.
Inside a workplace 401(k) plan, rebalancing transactions do not generate immediate taxable events, allowing adjustments between funds to occur efficiently without current-year capital gains consequences.
Common pitfalls in age-based account management
- Excessive Cash Drag: Holding high percentages of cash inside a long-term retirement account can cause savings to lose purchasing power to inflation over time.
- Extreme Conservatism Early On: Being overly cautious in early career stages can limit the long-term compounding potential needed to build a sufficient retirement balance.
- Emotional Reactivity: Attempting to time market swings by moving in and out of equities often leads to buying high and selling low, disrupting a disciplined allocation strategy.
Frequently asked questions about 401(k) asset allocation
Should asset allocation be based solely on age?
No. While age provides an approximate guide to your time horizon, it typically does not account for your risk tolerance, financial loss capacity, outside retirement savings, pension income, or distinct retirement timeline.
How much stock exposure should retirees maintain?
Many financial guidelines suggest retirees maintain between 30% and 50% of their portfolios in equities, depending on personal risk capacity. Holding an equity portion can help a portfolio generate growth that can outpace inflation throughout a retirement that may span 25 to 30 years or more.
Does rebalancing inside a 401(k) trigger taxes?
No. Rebalancing within a tax-advantaged account—such as a traditional 401(k) or Roth 401(k)—does not trigger immediate capital gains taxes or taxable events. You can review full regulatory guidance on plan structures directly through the IRS 401(k) Plan Information Resource.
Conclusion
Finding the right asset allocation commonly requires balancing age-based guidelines with your individual risk tolerance, outside income streams, and specific retirement goals. As life changes and markets fluctuate, a static, unmonitored portfolio can drift off course.
If you would like a personalized review of your workplace retirement plan, we invite you to learn more about how our independent fiduciary management works.
Some Key Takeaways
- Age-based formulas provide a general starting point, but they should not serve as rigid prescriptions for your portfolio.
- Your personal risk capacity, emotional risk tolerance, and outside income sources (like pensions or Social Security) can be just as critical as your age.
- Maintaining an appropriate equity allocation into retirement helps protect long-term purchasing power against inflation.
- Regular, disciplined rebalancing helps keep your investment portfolio aligned with your target risk profile over time.
Disclosure: This material is for educational purposes only and should not be considered personalized investment, legal, or tax advice. Investing involves risk, including the possible loss of principal. Asset allocation, diversification, and rebalancing strategies do not guarantee a profit or protect against loss in declining markets. Past performance is no guarantee of future results. Consult a qualified financial adviser or tax professional regarding your specific situation.