401k Hardship Withdrawal: Rules, Qualifying Reasons and Taxes
When a 401(k) hardship withdrawal may help
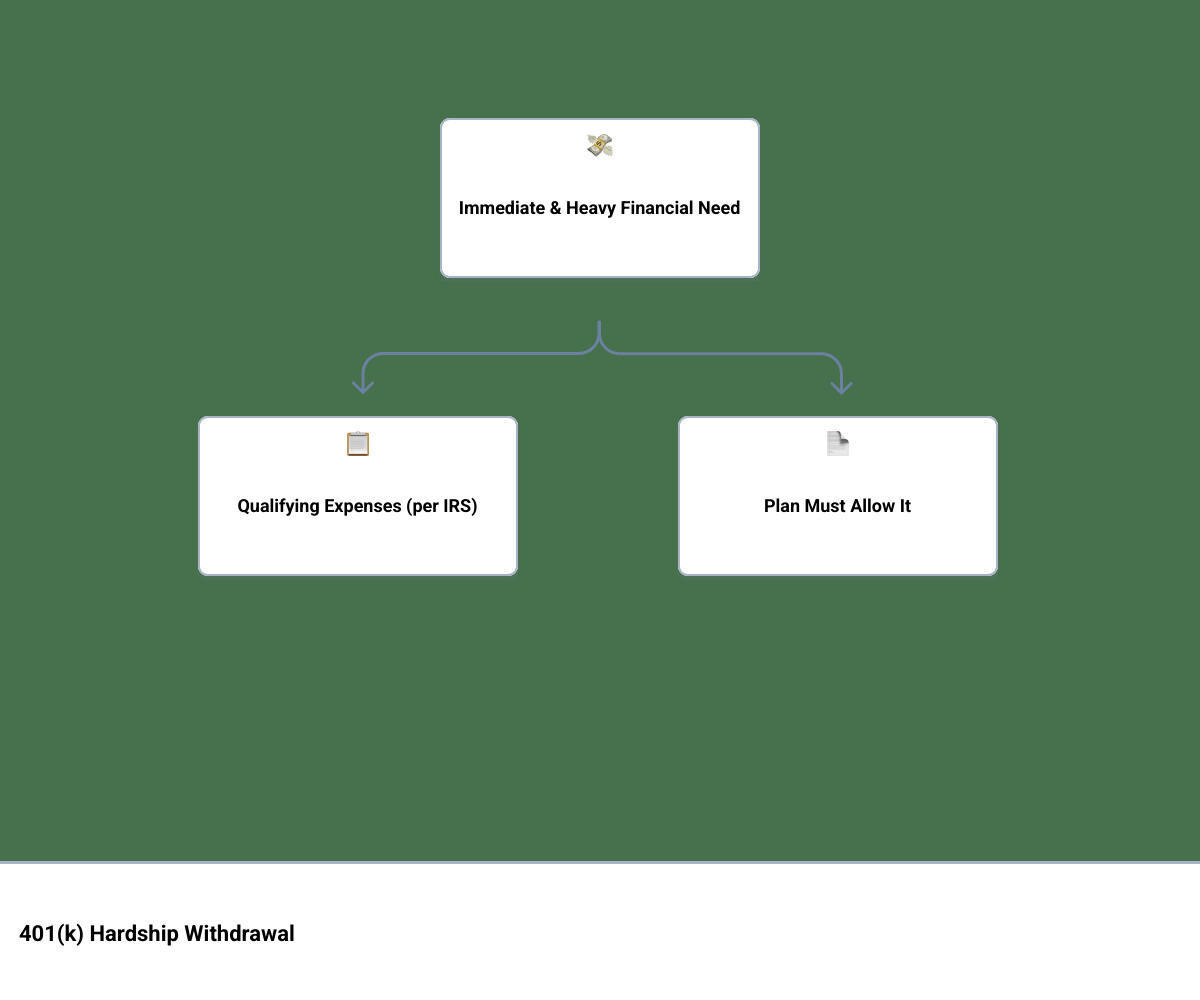
A 401(k) hardship withdrawal may let you take money from your retirement account for an immediate and heavy financial need, if your plan allows it. Qualifying needs can include certain medical bills, costs to prevent eviction or foreclosure, and eligible education expenses. The withdrawal does not need to be repaid, but it can reduce your future retirement savings. Check your plan’s Summary Plan Description to see which expenses it covers. The IRS hardship rules set the broader requirements.
Before requesting one, weigh the full cost: the withdrawal is generally taxable and may face an additional 10% tax if you are under age 59½, unless an exception applies. Your plan may let you certify your need without submitting documents upfront, but you should keep records. A plan loan or a separate emergency withdrawal may be worth comparing, if your plan offers them.
What is a 401(k) hardship withdrawal and how does it work?
A hardship distribution is an in-service withdrawal from your elective deferral account designed to satisfy an immediate and heavy financial need. However, workplace retirement plans are not legally required to offer this feature. You can only access your funds for an emergency if your employer has specifically written hardship provisions into the plan document.
Understanding the governing 401(k) hardship withdrawal rules starts with reviewing your plan’s Summary Plan Description (SPD). Under federal guidelines, the amount you take cannot exceed the exact dollar figure necessary to satisfy your financial need. You may, however, increase the gross distribution amount to cover anticipated federal, state, or local income taxes and potential penalties.
Unlike standard participant loans, a hardship withdrawal comes with no repayment obligation. Once the distribution occurs, those funds permanently leave your retirement account and cannot be rolled over into an IRA or redeposited into your workplace plan.
Hardship distribution vs. 401(k) loan
If you need emergency funds, your plan might offer the choice between a permanent hardship distribution and a plan loan. While both provide access to cash, their mechanics, tax treatments, and long-term consequences differ significantly.
| Feature | 401(k) hardship withdrawal | 401(k) loan |
|---|---|---|
| Repayment requirement | No repayment permitted | Must be repaid with interest (typically within 5 years) |
| Tax impact at distribution | Taxed as ordinary income | Tax-free if repaid on schedule |
| Early withdrawal penalty | 10% penalty if under age 59½ (unless exempt) | No penalty unless the loan defaults |
| Maximum limit | Limited to exact financial need | Up to 50% of vested balance or $50,000 (whichever is less) |
| Impact of job separation | None (funds are already distributed) | Balance may become due; unpaid amounts become taxable |
Understanding the difference between a 401(k) loan and a 401(k) withdrawal helps clarify the trade-offs. While a loan allows you to repay yourself through payroll deductions, repayments are made with after-tax dollars. If you leave your employer or cannot maintain payments, the outstanding balance can default, turning into a taxable distribution. Always consult the IRS 401(k) loan rules and your SPD to confirm eligibility.
Qualifying reasons for a hardship withdrawal from 401(k) accounts
To qualify under IRS safe harbor standards, your expense must fall into 1 of several strictly defined categories. The primary reasons for a hardship withdrawal from a 401(k) under safe harbor rules include:
- Medical expenses: Unreimbursed deductible medical care expenses for you, your spouse, your children, or designated dependents.
- Principal residence purchase: Costs directly related to purchasing your primary home, such as a down payment or closing fees (this does not include regular mortgage payments).
- Tuition and educational fees: Up to 12 months of post-secondary tuition, educational fees, and room and board for yourself, your spouse, or dependents.
- Eviction or foreclosure prevention: Payments necessary to prevent eviction from your primary residence or foreclosure on your primary mortgage.
- Funeral and burial costs: Expenses for the burial or funeral of your parent, spouse, child, or dependent.
- Casualty repairs: Certain expenses for repairing damage to your principal residence caused by a casualty event.
- Federally declared disasters: Certain expenses or losses incurred by a participant living or working in a designated disaster area.
General consumer obligations do not qualify. For example, high-interest credit card balances cannot be liquidated through a hardship distribution on their own, unless that unpaid debt has resulted in a legal notice of imminent eviction or foreclosure on your primary home.
Substantiation and self-certification for a 401(k) hardship withdrawal
Historically, plan administrators required participants to submit extensive paper documentation—such as hospital bills, eviction notices, or university tuition invoices—before approving a distribution.
Following the enactment of the SECURE 2.0 Act, plan administrators may permit employee self-certification for certain hardship requirements for plan years beginning after 2022. Under these provisions, you may be permitted to sign a written statement certifying that you have an immediate and heavy financial need, that the distribution does not exceed the necessary amount, and that you have no other reasonably available liquid assets.
This feature is not automatic across all plans. Employers must adopt these provisions, and administrators retain the right to request documentation if they have actual knowledge contradicting your claim. You should always retain all relevant financial records and invoices in case of an IRS audit or internal plan review.
Tax implications and 401(k) hardship withdrawal requirements
Taking a hardship distribution triggers distinct tax liabilities. For traditional 401(k) accounts, the entire distribution is treated as ordinary income and added to your taxable income for the year. Unlike certain eligible rollover distributions, hardship withdrawals are not subject to mandatory 20% federal tax withholding, though standard 10% voluntary federal withholding generally applies unless you opt out.
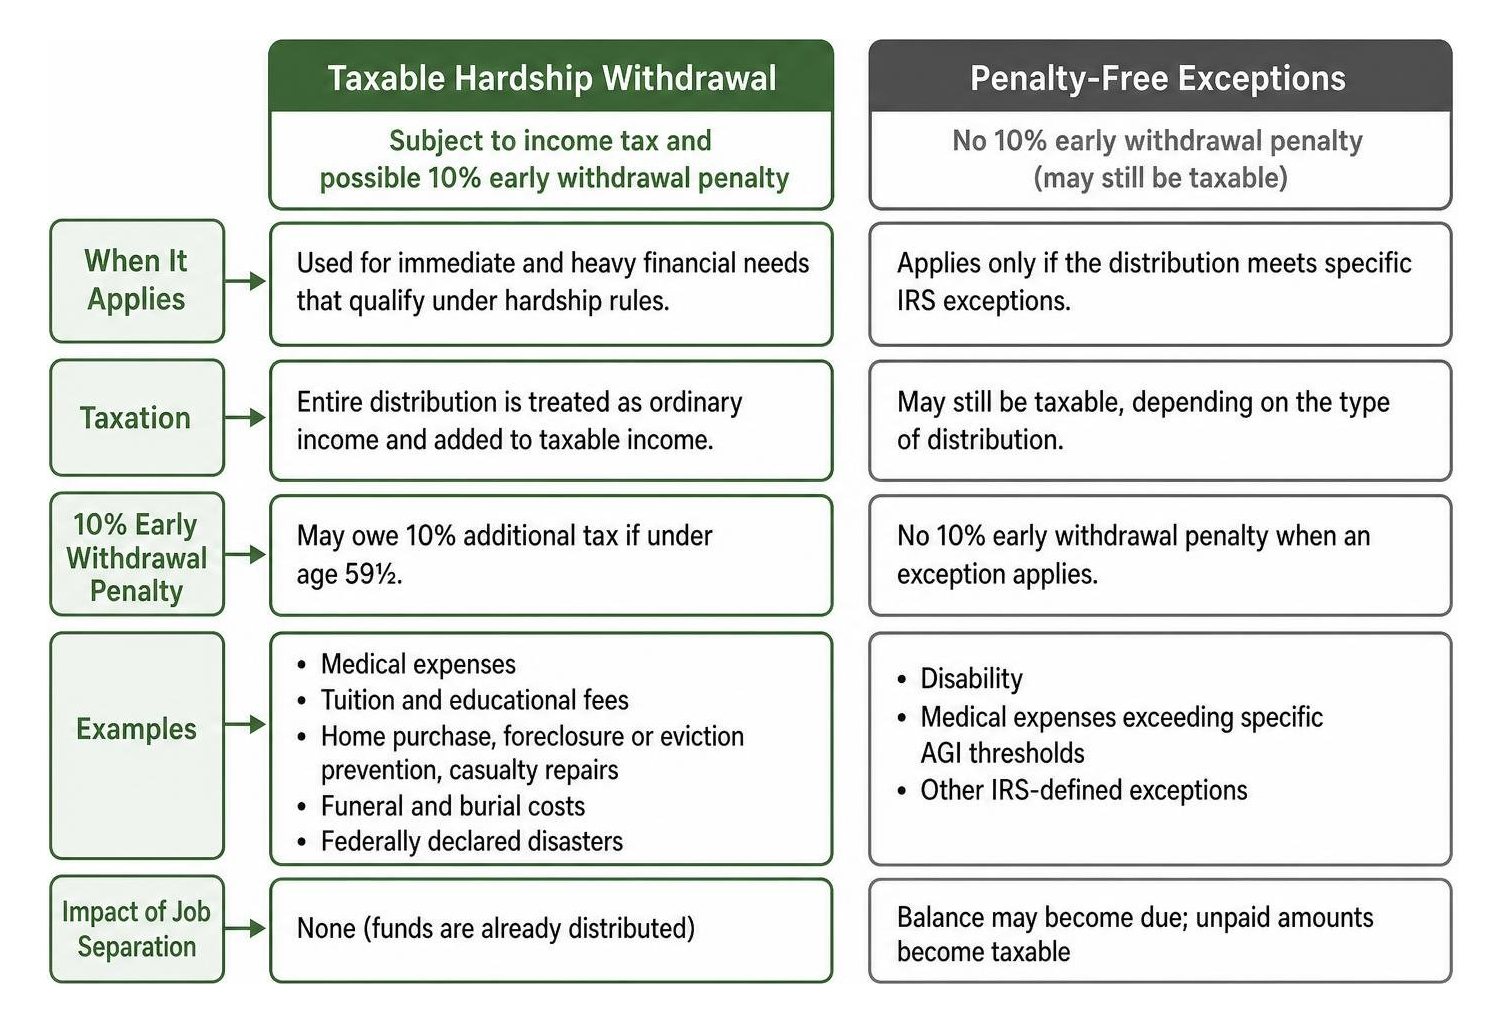
If you take a distribution before reaching age 59½, you may owe an additional 10% early withdrawal tax under IRS rules. Reviewing strategies for avoiding 401(k) withdrawal penalties can help you identify statutory exceptions, such as qualifying disability or medical expenses that exceed specific adjusted gross income thresholds. For complete details, consult the IRS guidance on early distributions.
Your plan administrator will report the distribution to the IRS using Form 1099-R. If you withdraw from a designated Roth 401(k), the portion representing your original contributions is typically distributed tax-free, while the earnings portion is taxable and subject to the 10% penalty unless the distribution meets qualified distribution requirements (holding the account for at least 5 years and reaching age 59½ or meeting a disability standard).
Long-term impact of a 401(k) hardship withdrawal on retirement growth
The most significant expense of a hardship withdrawal is often the lost compounding growth over time. Removing money from your investment portfolio locks in any market losses and prevents those dollars from generating future returns.
Under previous regulations, employees who took a hardship distribution were prohibited from making salary deferrals for 6 months. Treasury regulations eliminated this mandatory suspension rule, allowing participants to continue contributing immediately if their plan permits. Maintaining your contributions is critical to rebuilding your account balance over time.
Strategic alternatives to tapping your 401(k)
Before initiating a permanent withdrawal, you may want to evaluate alternative emergency options:
- SECURE 2.0 Emergency Personal Expense Distributions: For distributions after December 31, 2023, plans may optionally offer emergency distributions of up to $1,000 per calendar year. These distributions are exempt from the 10% early withdrawal tax and can be repaid within 3 years, subject to plan rules.
- 401(k) Participant Loans: If allowed by your plan, borrowing against your vested balance enables you to access funds without triggering income taxes or early distribution penalties, provided you follow the repayment schedule.
- Dedicated Emergency Reserves: Using non-retirement liquid savings or dedicated emergency funds protects your tax-advantaged accounts from premature depletion.
- Health Savings Accounts (HSAs): If facing medical expenses and enrolled in an eligible high-deductible health plan, using an HSA allows you to pay qualified medical costs completely tax-free.
- Education-Specific Financing: Exploring federal student loans or payment plans can often be more cost-effective than liquidating retirement savings for higher education.
Some takeaways: What think you need to know before withdrawing
- Plan permission required: Hardship withdrawals are only available if explicitly permitted by your employer’s plan document.
- Strict IRS criteria: You must meet safe harbor standards for an immediate and heavy financial need, limited strictly to the required amount.
- Permanent tax cost: Distributions from pre-tax accounts incur ordinary income tax and a potential 10% early withdrawal tax if under age 59½.
- No repayment allowed: Hardship funds cannot be redeposited or rolled over into another retirement vehicle.
- Evaluate alternatives first: Consider plan loans, emergency expense distributions, or non-retirement savings before liquidating long-term investments.
Frequently asked questions about 401(k) hardship withdrawals
What are the main reasons for a hardship withdrawal from 401(k) plans?
The primary safe harbor reasons include qualifying unreimbursed medical care, primary residence purchase costs, post-secondary tuition and fees, prevention of eviction or foreclosure, funeral expenses, certain casualty repairs, and expenses related to federally declared disasters. Your plan document specifies which of these reasons are adopted.
Can I pay back a 401(k) hardship withdrawal later?
No. Hardship distributions are permanent distributions of your retirement savings and cannot be repaid or rolled over into an IRA. However, current rules allow you to continue making regular salary deferrals to your plan without waiting through a mandatory suspension period.
How does SECURE 2.0 change 401(k) hardship withdrawal rules?
SECURE 2.0 allows plan administrators to accept employee self-certification of hardship events for plan years beginning after 2022, simplifying the administrative request process. It also created an optional emergency personal expense distribution feature for distributions after December 31, 2023, allowing up to $1,000 annually penalty-free, if adopted by your plan sponsor.
Conclusion
Deciding how to manage unexpected financial pressure requires careful consideration of both immediate needs and long-term security. If you are navigating workplace retirement decisions and want fiduciary support without moving your account, the 401(k) Maneuver team is here to help. You can learn how 401(k) account management works to review your options in a calm, no-pressure conversation.
Disclosure: 401(k) Maneuver is a business name of Royal Fund Management, LLC, an SEC-registered investment adviser. This article is provided for educational purposes only and does not constitute personalized financial, tax, or legal advice. Investing involves risk, including the possible loss of principal. Past performance does not guarantee future results. Consult a qualified professional regarding your specific situation before making distribution decisions.